Gold bullion retirement accounts have gained popularity in recent times as traders seek to diversify their retirement portfolios past traditional belongings like stocks and bonds. These accounts allow people to hold physical gold bullion as a part of their retirement savings, providing a hedge in opposition to inflation and economic uncertainty. This report will discover the basics of gold bullion retirement accounts, their benefits and drawbacks, tax implications, and how one can set one up.
Understanding Gold Bullion Retirement Accounts
Gold bullion retirement accounts are specialized accounts that enable investors to incorporate physical gold of their retirement portfolios. In contrast to traditional retirement accounts, which typically hold stocks, bonds, or mutual funds, these accounts allow for the direct ownership of gold bars or coins. The commonest types of retirement accounts that can be utilized for investing in gold include Particular person Retirement Accounts (IRAs) and 401(okay)s.
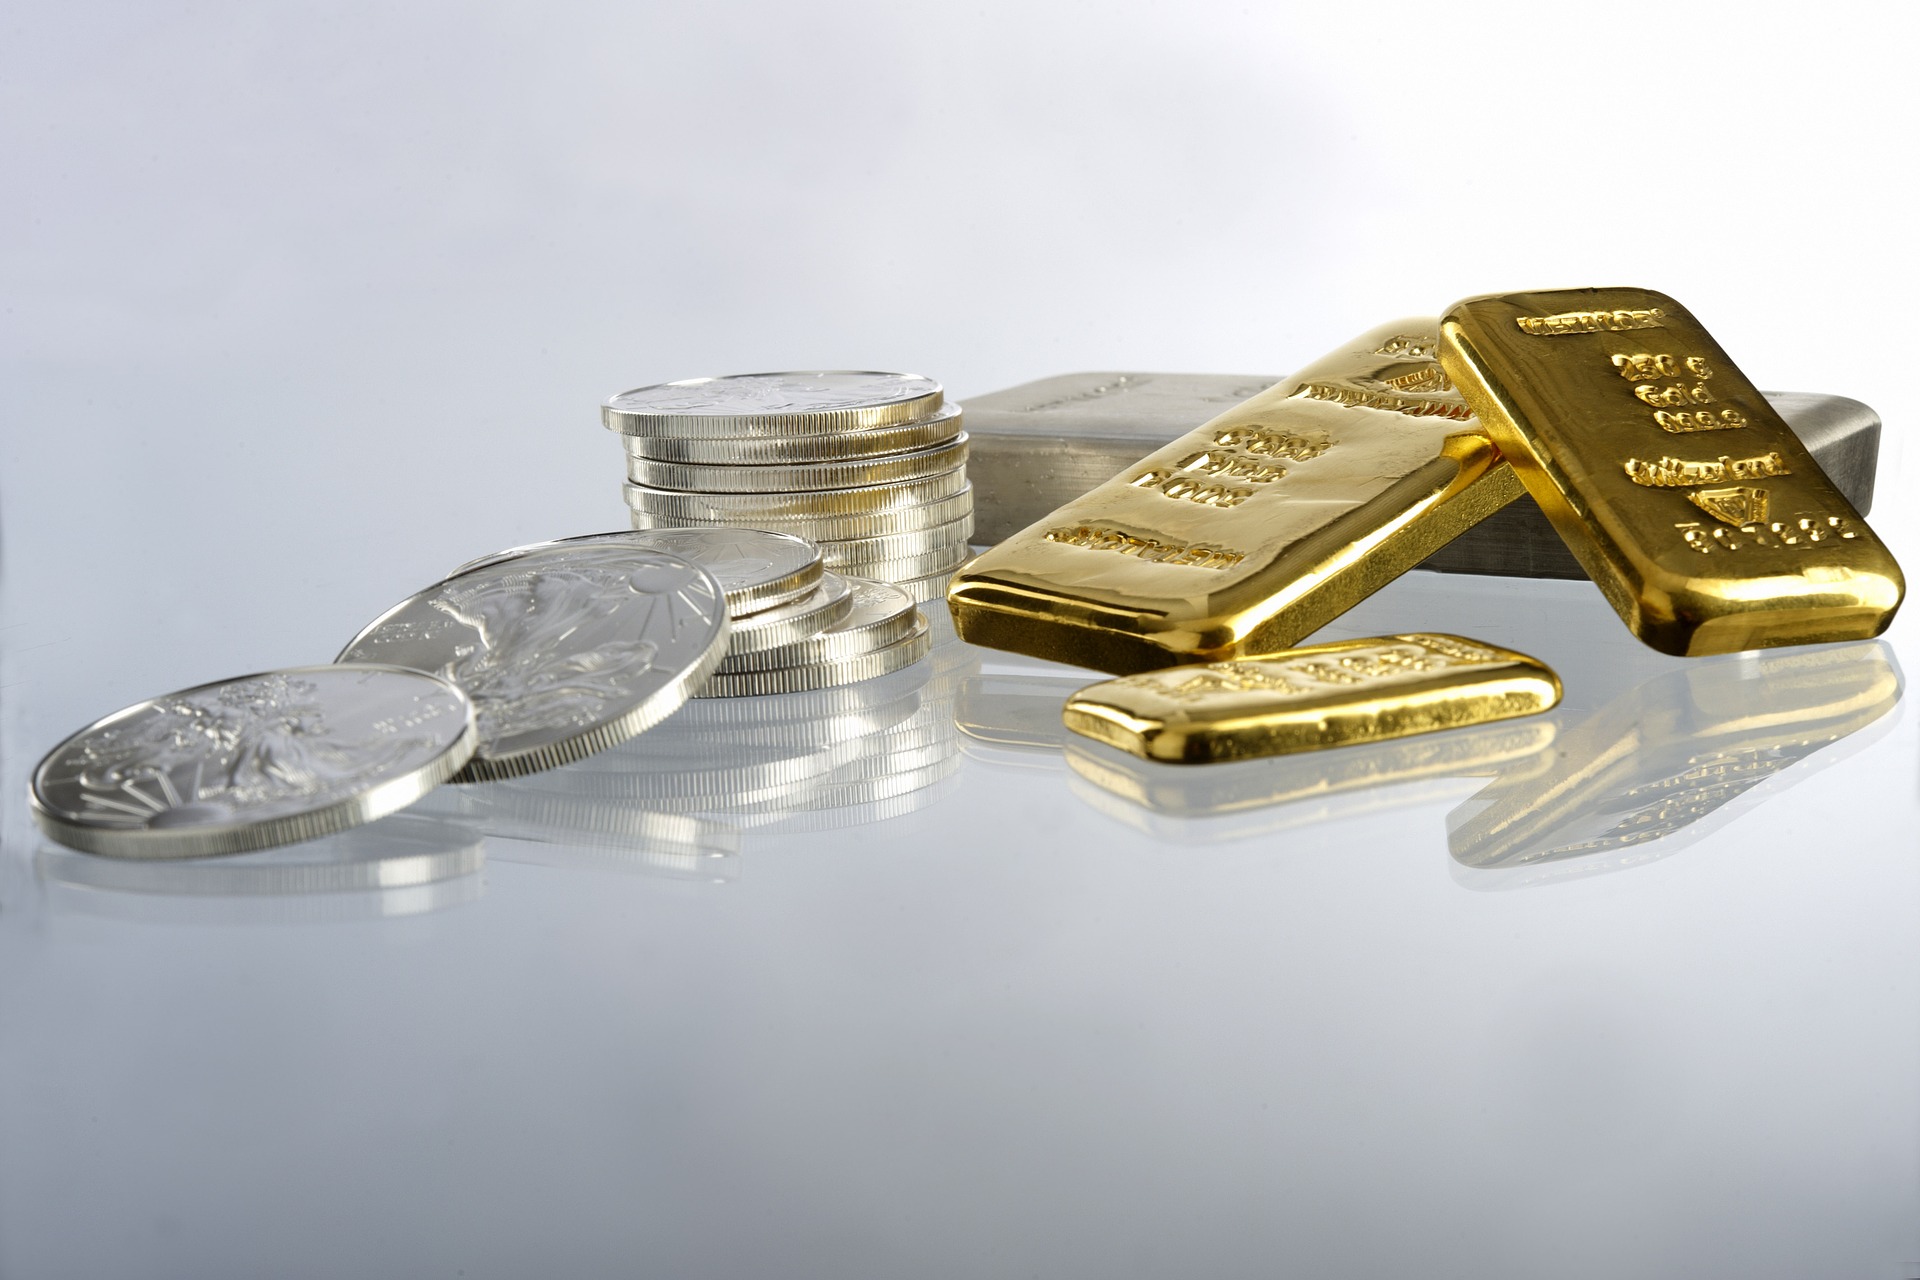
To qualify for tax benefits, gold bullion must meet specific purity standards set by the inner Revenue Service (IRS). Usually, only gold coins and bars which are no less than 99.5% pure are eligible for inclusion in a gold-backed retirement account. Popular choices embrace American Gold Eagles, Canadian Gold Maple Leafs, and gold bars from acknowledged refiners.
Advantages of Gold Bullion Retirement Accounts
- Inflation Hedge: Gold has traditionally been seen as a safe-haven asset during instances of economic instability. By together with gold bullion in a retirement account, investors can protect their financial savings from inflation and foreign money devaluation.
- Portfolio Diversification: Gold typically has a low correlation with traditional asset lessons like stocks and bonds. By diversifying with gold, buyers can cut back general portfolio danger and improve potential returns.
- Tangible Asset: In contrast to stocks or bonds, gold is a bodily asset that traders can hold. This tangibility can present peace of mind, especially throughout periods of financial turmoil.
- Tax Advantages: Gold bullion retirement accounts can offer tax-deferred progress, much like conventional IRAs. If you loved this post and you would like to receive more details regarding Gold-Ira please visit the web-site. Which means that investors don’t pay taxes on good points till they withdraw funds, allowing for potentially larger compounding over time.
Drawbacks of Gold Bullion Retirement Accounts
- Storage and Insurance Costs: Physical gold requires secure storage, which may incur extra costs. Traders could must pay for vault storage or insurance to protect their holdings, which can eat into returns.
- Limited Liquidity: Selling physical gold might be less simple than liquidating stocks or bonds. Investors may face delays or further prices when changing gold again into money.
- Market Volatility: While gold is often thought-about a protected-haven asset, its price can nonetheless be unstable. Buyers have to be prepared for fluctuations in gold costs, which might affect the worth of their retirement accounts.
- Contribution Limits: Like conventional IRAs, there are annual contribution limits for gold bullion retirement accounts. This may occasionally limit how a lot investors can allocate to gold each year.
Tax Implications
Investing in gold bullion by means of a retirement account comes with particular tax implications. Usually, gold held in an IRA just isn’t topic to capital good points tax until the investor withdraws it, permitting for tax-deferred development. Nevertheless, when gold is withdrawn from the account, it’s handled as bizarre income and taxed accordingly.
It’s essential for traders to concentrate on the potential penalties associated with early withdrawals. If an individual withdraws funds from their retirement account before the age of 59½, they could incur a 10% early withdrawal penalty in addition to strange earnings taxes.
Furthermore, if gold is taken as a distribution somewhat than offered, it could also be topic to additional taxes and charges. Traders should seek the advice of with a tax professional to grasp the complete implications of investing in gold bullion via a retirement account.
Organising a Gold Bullion Retirement Account
Establishing a gold bullion retirement account usually includes several steps:
- Choose a Custodian: Traders should choose a custodian that focuses on self-directed IRAs or gold retirement accounts. The custodian will handle the account, handle transactions, and guarantee compliance with IRS laws.
- Open the Account: After selecting a custodian, traders can open a self-directed IRA or gold retirement account. This course of often includes filling out an software and providing obligatory identification and financial data.
- Fund the Account: Traders can fund their gold retirement account by contributions, rollovers from different retirement accounts, or transfers. It is important to adhere to contribution limits and IRS rules during this process.
- Purchase Gold Bullion: Once the account is funded, investors can purchase eligible gold bullion through the custodian. The custodian will facilitate the purchase and be sure that the gold meets IRS requirements.
- Storage and Insurance coverage: The physical gold must be saved in an authorized depository. The custodian will arrange for safe storage, and traders should consider obtaining insurance coverage for added safety.
Conclusion
Gold bullion retirement accounts present a singular opportunity for investors seeking to diversify their retirement portfolios and protect their financial savings from inflation and financial uncertainty. Whereas there are important advantages, resembling tax advantages and portfolio diversification, traders must additionally consider the drawbacks, including storage prices and market volatility. By understanding the tax implications and following the mandatory steps to set up an account, people can effectively incorporate gold bullion into their retirement planning strategy. As at all times, it’s advisable to seek the advice of with financial and tax professionals before making investment decisions to ensure compliance and alignment with particular person monetary goals.